Italy Removes E-Invoicing Audit Incentive for Forfettario Regime
As of 2026, Italy has formally eliminated a key compliance incentive for small businesses operating under the *regime forfettario*, marking a significant policy shift in the country's tax-digitization landscape. The change removes an audit-frequency discount previously granted to VAT-registered sole traders and small businesses using e-invoicing, effectively normalizing their audit exposure with the broader taxpayer population.
Context
The regime forfettario is Italy's simplified flat-rate tax regime, designed to reduce administrative burdens for small businesses and sole traders below specific revenue thresholds. Historically, taxpayers enrolled in this regime who adopted mandatory e-invoicing through the Sistema di Interscambio (SdI) platform benefited from a reduced frequency of tax audits. This incentive served as both a compliance carrot and a tangible reward for early adoption of digital tax practices.
The policy shift, formalized by Italy's Agenzia delle Entrate, takes effect from 2026-06-26 reporting date. It represents a deliberate recalibration by Italian tax authorities, recognizing that e-invoicing adoption within the forfettario cohort has reached sufficient maturity. This change is distinct from technical updates to the SdI infrastructure or broader VAT compliance reforms, reflecting a strategic normalization of audit risks for this segment.
What's Changing
The primary change is the elimination of the audit-frequency discount for forfettario taxpayers using e-invoicing. Previously, participation in the SdI platform was met with preferential audit treatment, effectively reducing compliance scrutiny. Moving forward, these taxpayers will be subject to the same general audit standards applied across Italy's broader taxpayer population.
E-invoicing via the SdI platform remains mandatory for most forfettario taxpayers, following the phased expansion of Italy's e-invoicing mandate. However, the removal of the audit incentive shifts the enforcement calculus for this segment. Compliance vigilance must now be maintained on its own merits, without the prior buffer of reduced scrutiny.
Implications for Forfettario Taxpayers
The policy change has immediate implications for partite IVA operating under the forfettario regime. The removal of the audit incentive necessitates increased focus on compliance processes, as taxpayers can no longer rely on preferential treatment as a result of their e-invoicing participation. This normalization of audit exposure aligns the forfettario cohort with broader taxpayer standards, reflecting mature adoption of digital compliance tools.
For IT providers serving this segment, the change underscores the importance of robust e-invoicing solutions that facilitate compliance beyond mere audit incentives. The focus shifts to ensuring seamless integration with the SdI platform and maintaining accurate, timely invoice processing to mitigate audit risks.
Outlook
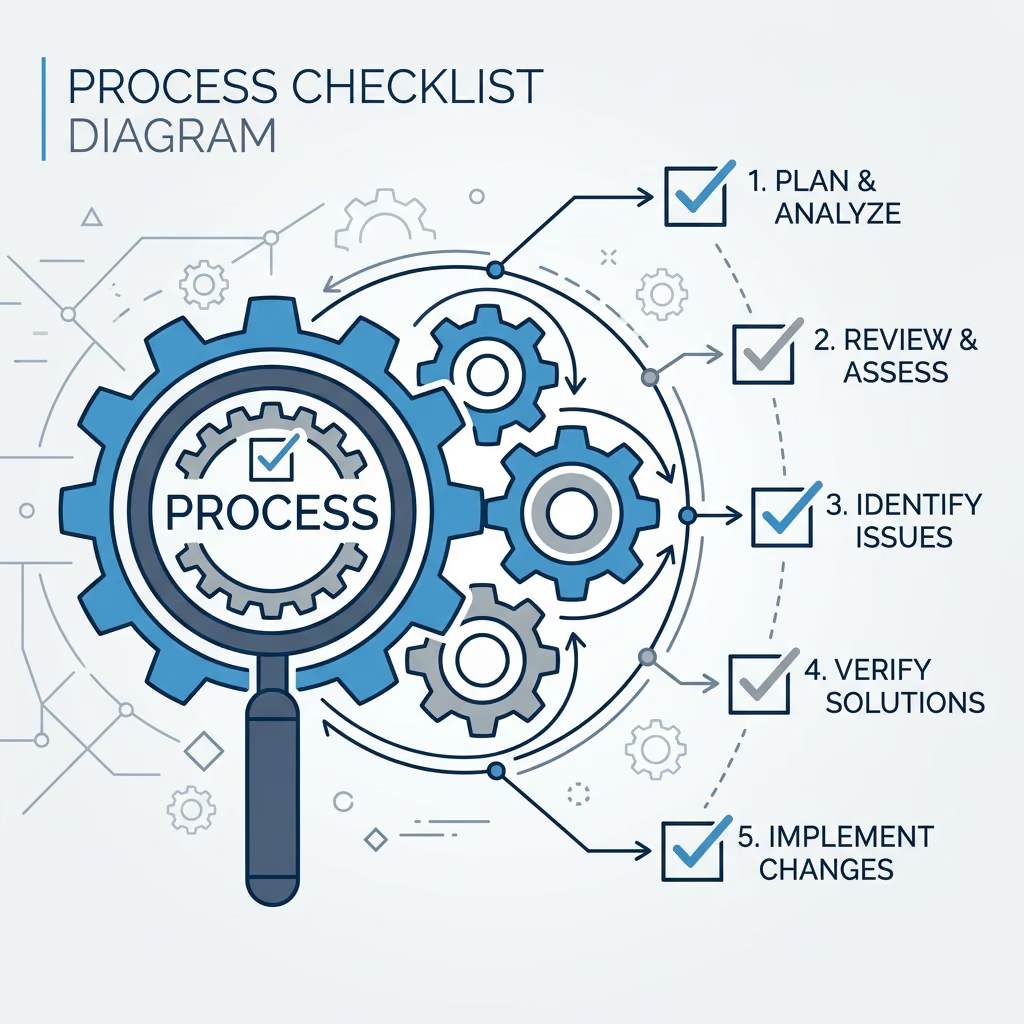
Looking ahead, affected taxpayers should prepare for increased compliance vigilance. While the audit-frequency discount is removed, the core benefits of e-invoicing—such as streamlined invoicing processes and reduced administrative burdens—remain intact. Taxpayers should leverage these advantages to maintain compliance without relying on preferential audit treatment.
For draft writers covering Italy's tax-digitization landscape, this development highlights the evolving nature of compliance incentives. As e-invoicing adoption matures, policy shifts like this one will likely become more common, reflecting the normalization of digital compliance practices. Watch for further adjustments to audit standards and potential reforms targeting other simplified tax regimes.